
Guide
The Complete Guide to Gold and Silver Coin Grading
Walk into the numismatic side of any serious precious metals conversation and you will encounter a vocabulary that
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Every precious metals buyer eventually asks the same question in one form or another: why did gold go up today? Why is it falling when inflation is high? Why does it seem to move in the opposite direction from stocks sometimes and with them at other times? The gold price is not arbitrary and it is not manipulated in any simple sense — it is the product of a specific set of interacting factors that, once understood, make gold price movements consistently interpretable if never fully predictable. This guide explains every significant driver of the gold price, how they interact with each other, and what they mean for investors holding physical gold bars and coins.
Understanding these drivers does not enable market timing — no one can reliably predict short-term gold price movements, and investors who try consistently underperform those who dollar-cost average systematically. What it does enable is informed conviction — the ability to hold through volatility because you understand what is driving price movements and why your long-term thesis remains intact despite short-term fluctuations.
Of all the variables that drive the gold price, real interest rates — the difference between nominal interest rates and inflation — have the strongest and most consistent documented relationship with gold. Understanding this relationship is the foundation of understanding the gold market.
Gold pays no yield. It generates no income. A holder of physical Gold Eagles receives no dividends, no coupon payments, no rental income. This means that gold’s opportunity cost — what you give up by holding gold instead of yield-bearing alternatives — is entirely determined by what yield-bearing alternatives offer in real terms.
When real interest rates are negative — when inflation exceeds nominal interest rates, meaning that yield-bearing assets are losing purchasing power despite their nominal yield — gold’s opportunity cost is effectively negative. Holding gold, which loses no nominal value, becomes preferable to holding a bond that is losing purchasing power. Gold demand rises; gold price rises.
When real interest rates are strongly positive — when nominal rates well exceed inflation, meaning yield-bearing assets are genuinely growing purchasing power — gold’s opportunity cost rises sharply. Investors who can earn 4% or 5% in real terms from Treasury bonds have less incentive to hold non-yielding gold. Gold demand falls; gold price faces pressure.
This is why gold fell sharply from 1980 to 2000 despite persistent inflation during much of that period — real interest rates were often strongly positive because the Fed raised nominal rates aggressively. It is why gold rose dramatically from 2001 to 2011 — real rates were often negative or near-zero. It is why gold faced pressure in 2022-2023 even as inflation ran high — the Fed raised nominal rates faster than inflation, pushing real rates positive again. And it is why any expectation of Fed rate cuts — which reduce nominal rates and often push real rates negative again — is typically bullish for gold prices.
For investors in Gold IRAs and personal gold positions, tracking real interest rates — calculable by subtracting CPI inflation from the 10-year Treasury yield — provides the most reliable ongoing context for gold price direction.
Gold is priced globally in US dollars. This creates a direct mathematical relationship: when the dollar strengthens against other currencies, an ounce of gold costs more in those other currencies — reducing demand from non-dollar buyers — and the dollar price of gold tends to fall. When the dollar weakens, gold becomes cheaper in other currencies, non-dollar demand rises, and the dollar price tends to rise.
This inverse relationship between the dollar and gold is one of the most consistently observed in financial markets — though it is not absolute. The relationship is strongest in the short term and weakens over longer time periods, where other drivers dominate. The DXY Dollar Index — a weighted measure of the dollar against a basket of major currencies — is the standard tool for tracking this driver. When DXY rises, watch for gold price pressure. When DXY falls, conditions are typically supportive for gold.
For US investors holding physical gold bars and gold coins, a weakening dollar is doubly beneficial: the dollar gold price rises, and the real purchasing power of the dollar they would use to buy anything else falls. This is one of the reasons gold functions as an effective inflation hedge — dollar weakness and inflation often occur simultaneously, and gold benefits from both.
Gold is universally understood as a monetary safe haven — an asset that holds value when other assets, institutions, or currencies come under stress. This understanding creates a specific demand pattern: when geopolitical tension rises, when financial institutions face credibility challenges, or when systemic risk in financial markets elevates, gold demand increases as investors seek assets outside the at-risk systems.
The mechanism is not subtle. When a major bank fails, investors who hold physical gold do not have counterparty exposure to that bank. When a government’s currency credibility weakens, gold priced in that currency maintains its purchasing power. When equity markets fall sharply — particularly in stress events rather than ordinary corrections — gold often holds value or rises, because investors are selling financial assets to buy genuine stores of value outside the financial system. This is why central banks accelerated gold buying after Russian reserves were frozen in 2022 — a direct demonstration of what geopolitical risk means for assets inside versus outside the financial system.
The challenge for investors is that geopolitical risk is the least predictable of gold’s major drivers. You cannot reliably time the purchase of gold around specific geopolitical events — by the time an event is public knowledge and clearly priced in, the gold price response has often already occurred. The appropriate strategy is to hold physical gold as a permanent geopolitical risk hedge rather than attempting to buy it specifically before events.
A distinction that confuses many new gold investors: gold responds more strongly to inflation expectations than to reported inflation. By the time CPI data is published showing high inflation, the market has often already priced much of the gold response based on earlier expectation signals — monetary policy statements, forward guidance, money supply data, commodity price trends.
This is why gold sometimes appears to not respond to high reported inflation — the response already happened when expectations were formed. And it is why gold sometimes rises even when current inflation is moderate — if markets expect inflation to accelerate, gold can price in that expectation before the data confirms it.
The practical implication: watch leading inflation indicators rather than lagging reported data. Money supply growth (M2), commodity prices, breakeven inflation rates from Treasury Inflation-Protected Securities (TIPS), and Federal Reserve communication are better forward indicators for gold than monthly CPI releases. Our inflation and gold guide covers the relationship between measured inflation and gold price performance in depth.
Beyond the fundamental drivers above, gold price is also influenced by investment flows — ETF buying and selling, futures positioning by commodity funds, and speculative trading — that can amplify price movements in either direction without always reflecting fundamental changes.
Gold ETFs like GLD and IAU hold physical gold on behalf of shareholders. When investment demand for gold exposure rises — typically correlating with the fundamental drivers above — ETF inflows require the funds to buy physical gold, amplifying price movement. When investment demand falls, ETF outflows create selling pressure. The Commitment of Traders (COT) report published weekly by the CFTC shows the positioning of large and small speculators in gold futures — a data point that technical traders use to assess whether the market is over-positioned in one direction.
For physical gold investors — holders of Gold Eagles, Gold Maple Leafs, PAMP bars, and kilo bars — speculative ETF and futures flows are largely noise around the fundamental signal. They create short-term volatility that makes dollar-cost averaging more effective than lump-sum timing for building a position. Over multi-year periods, the fundamental drivers — real interest rates, dollar strength, geopolitical risk, inflation — dominate speculative flows.
As detailed in our central bank gold buying guide, institutional sovereign demand is now a structural feature of the gold market rather than a cyclical one. Central banks buying over 1,000 tonnes annually — as they did in 2022 and 2023 — absorb supply that would otherwise be available to other buyers, creating a demand floor that did not exist during the net-selling era of the 1990s.
This structural demand floor interacts with all the other drivers: when real rates rise and speculative investment demand falls, central bank buying can cushion the price decline. When geopolitical risk rises and investment demand spikes, central bank buying adds to the momentum. The effect is asymmetric — central bank demand is typically stronger on dips (buying on weakness) than on rallies — providing support rather than fuel, but meaningful support at a persistent, multi-year scale.
Gold price movements are multi-causal and often appear contradictory because different drivers are pulling in different directions simultaneously. Rising inflation is bullish for gold, but if the Fed responds with rate hikes that push real rates positive, the rate effect can override the inflation effect. Geopolitical risk is bullish, but if it triggers a risk-off event that strengthens the dollar simultaneously, the dollar effect partially offsets the safe-haven effect.
The investor’s practical takeaway: understanding the drivers makes you a better holder, not a better timer. When gold falls despite conditions that seem supportive, knowing that short-term speculative positioning or dollar strength may be the temporary override — while real rates, structural central bank demand, and geopolitical risk remain as long-term supports — enables you to hold through volatility with informed conviction rather than reactive uncertainty.
For the silver spot price dynamics that parallel but differ from gold, industrial demand adds a layer of economic sensitivity that pure gold price analysis does not capture. The gold-to-silver ratio provides the framework for understanding how gold and silver price movements interact and diverge.
Q: Why does gold go up when the dollar falls?
A: Gold is priced globally in US dollars. When the dollar weakens against other currencies, gold becomes less expensive in those currencies — stimulating non-dollar demand. This increased demand pushes the dollar gold price higher. The relationship is inverse and well-documented: a falling dollar is typically bullish for gold; a rising dollar creates price headwind.
Q: Why does gold fall when interest rates rise?
A: Higher interest rates increase the opportunity cost of holding non-yielding gold — investors can earn returns in yield-bearing assets that gold cannot match. The relationship is specifically with real interest rates (nominal rates minus inflation). When rate hikes push real rates strongly positive, gold faces meaningful selling pressure as the attractiveness of yield-bearing alternatives rises.
Q: Does gold always rise during inflation?
A: Not always in the short term. Gold’s relationship to inflation is strongest over multi-year periods. In the short term, if the Fed responds to inflation with aggressive rate hikes that push real rates positive, the rate effect can overwhelm the inflation effect, causing gold to fall despite high reported inflation. The key variable is real interest rates — not nominal rates or CPI in isolation.
Q: How does geopolitical tension affect gold price?
A: Geopolitical tension increases safe-haven demand for gold as investors seek assets outside financial systems that may be at risk. The effect is most pronounced for events that specifically threaten financial system credibility — banking crises, currency crises, sanctions actions — rather than ordinary political conflicts. The challenge is that gold often prices in geopolitical risk before events become fully public.
Q: Should I try to time gold purchases based on these drivers?
A: Evidence consistently shows that systematic dollar-cost averaging outperforms market timing for most precious metals investors. Understanding the drivers enables informed conviction during volatility — knowing why prices are moving and whether your long-term thesis remains intact — rather than enabling profitable short-term trading, which requires consistently correct forecasting of multiple interacting variables simultaneously.

Investment-grade gold, priced with the live market and fully insured.
Prices, new stock and new guides. No spam.
Walk into the numismatic side of any serious precious metals conversation and you will encounter a vocabulary that
Inflation is not an abstract economic concept — it is the measured, documented erosion of what your money
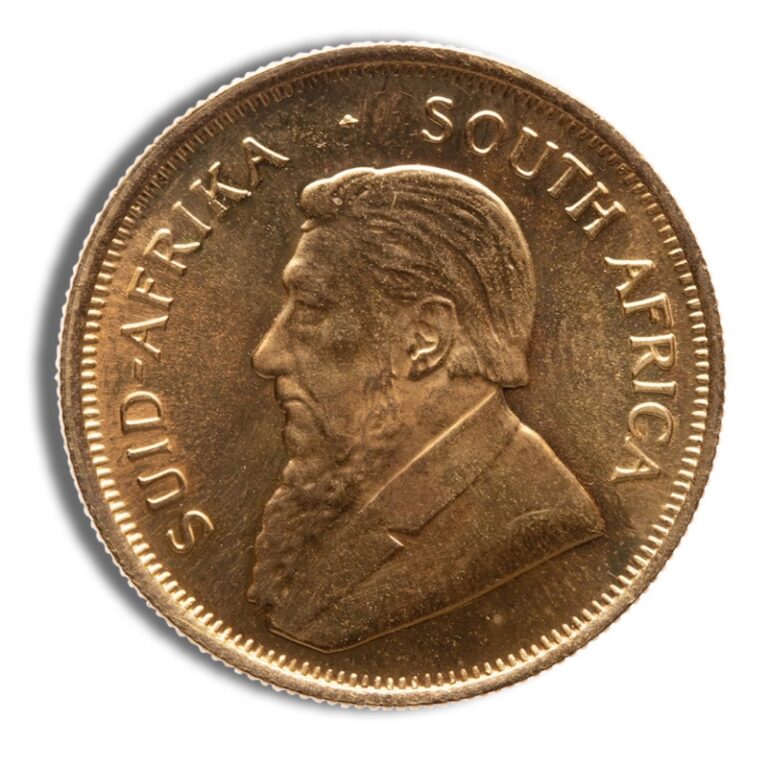
Among the analytical tools that serious precious metals investors use, one stands out for its simplicity and its
Email us and a real person will help you choose the right gold for you.