Guide
The Complete Guide to Gold and Silver Coin Grading
Walk into the numismatic side of any serious precious metals conversation and you will encounter a vocabulary that
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Discover our collection of gold coins in a variety of weights, designs, and trusted mint options. Whether you’re investing, building your collection, or looking for a timeless gift, our gold coins offer a convenient way to own physical gold.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Makes it simple to buy gold and precious metals with confidence. We offer a carefully selected range of gold bars, gold coins, platinum, silver, and other precious metals for investors, collectors, and anyone looking to own tangible assets.
Every serious precious metals investor eventually faces a question they did not anticipate when they made their first gold purchase: what happens to this when I am gone? Physical gold and silver are uniquely capable assets — they hold value across generations, they require no institution to maintain them, and they pass directly from person to person in a way that paper assets cannot. But this same directness that makes physical precious metals valuable also creates specific estate planning considerations that are quite different from what applies to brokerage accounts, retirement funds, or real estate. Getting these considerations right is the difference between your precious metals reaching your intended heirs efficiently and your heirs facing confusion, legal complications, or significant unnecessary tax costs.
This guide covers the complete estate planning picture for physical precious metals — documentation requirements, storage and access considerations, tax treatment for heirs, IRA-held metals, and the practical steps that every precious metals owner should take regardless of the size of their holding.
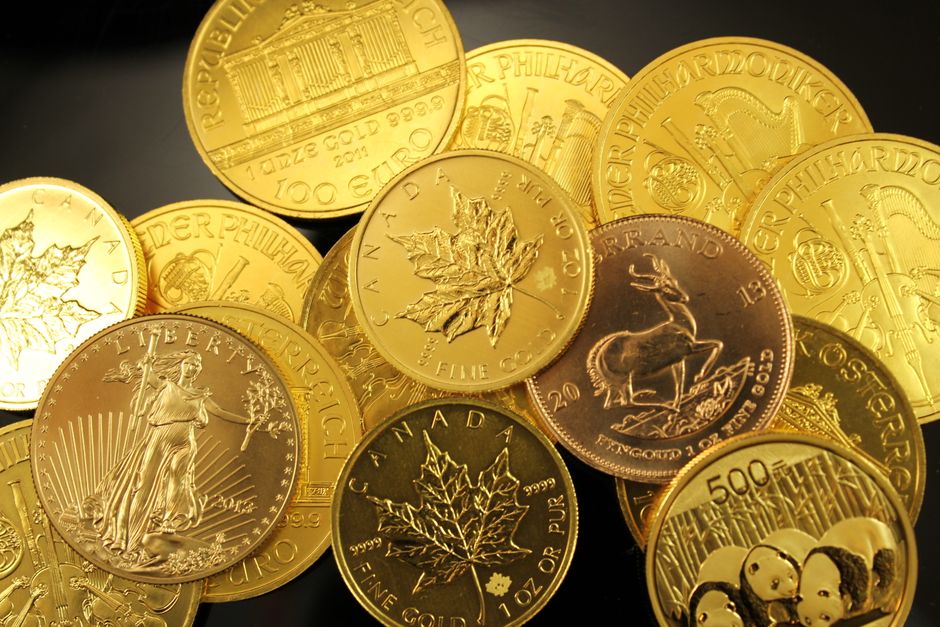
A brokerage account is self-documenting — the institution maintains records of what you own, sends statements, and has processes for transferring assets to beneficiaries upon death. Physical gold and silver sitting in a home safe are entirely self-documenting only to the degree that you have documented them. If you die with Gold Eagles, Silver Maple Leafs, and PAMP Suisse bars in a safe that your heirs do not know exists, those assets may never be found. If they are found but not documented, your heirs cannot establish acquisition cost for tax purposes, cannot verify the coins against counterfeits, and cannot efficiently evaluate what they have inherited.
The documentation solution is straightforward but requires deliberate action:
Maintain a precious metals inventory. A simple document — updated whenever you make a purchase or sale — listing every piece by product name, weight, purity, refiner, serial number (where applicable), acquisition date, and acquisition cost. This document establishes your cost basis for each item, which determines your heirs’ tax obligations. Store this inventory separately from the metals themselves — in encrypted digital storage, with your attorney, or in a safety deposit box — and ensure your estate executor knows where to find it. Our guide to reading assay cards explains where to find serial numbers and other identifying information on every type of bar and coin.
Include precious metals in your will explicitly. A will that says “I leave my tangible personal property to my children” may or may not include precious metals depending on how your jurisdiction defines tangible personal property. Specify your precious metals holdings explicitly — “my gold coins, silver bars, and all precious metals bullion” — and designate specific beneficiaries or a clear distribution method. If you want specific pieces to go to specific people, identify them by description and serial number where possible.
Tell at least one trusted person. Your attorney, your estate executor, or a trusted family member should know that you own physical precious metals, where they are stored, and how to access them. Precious metals found during estate settlement without prior knowledge of their existence often create legal complications around authenticity verification, valuation, and equitable distribution among multiple heirs.
Physical gold and silver receive specific tax treatment in the US that differs from most financial assets. Understanding this before you create your estate plan — and communicating it to your heirs — prevents surprises.
Capital gains during your lifetime. When you sell precious metals, gains are taxed as collectibles at up to 28% for long-term holdings (held more than one year) — higher than the standard 15-20% long-term capital gains rate on equities. This is a cost you manage during your lifetime through strategic selling and holding periods.
The step-up in basis at death. This is the most important estate planning concept for precious metals owners. When your heirs inherit physical precious metals, the tax basis of those metals steps up to the fair market value at the date of your death. This means your heirs’ capital gains calculation starts from the date-of-death value — not from what you originally paid. If you purchased Gold Eagles for $1,200 each and they are worth $3,200 each at your death, your heirs inherit them with a $3,200 basis. If they sell immediately at $3,200, they owe zero capital gains. The $2,000 per-coin appreciation that occurred during your lifetime passes to your heirs completely free of capital gains tax.
This step-up in basis is one of the most powerful estate planning advantages available for long-term precious metals investors. It is a significant argument for holding physical gold and silver — particularly large kilo bars, 10 oz bars, and 100 oz silver bars that have appreciated significantly — as long-term family wealth assets rather than short-term trading instruments.
Estate tax. Physical precious metals are included in the gross estate for federal estate tax purposes at fair market value at the date of death. For estates below the federal exemption threshold (currently over $13 million per individual, subject to legislative change), this creates no estate tax liability. For larger estates, precious metals holdings are part of the taxable estate and should be accounted for in estate planning with a qualified estate attorney. State estate taxes vary significantly and may apply at lower thresholds.
Precious metals held in a self-directed Gold IRA or Silver IRA follow IRA inheritance rules rather than the rules that apply to personally held metals — and the differences are significant.
Inherited IRAs. When a spouse inherits a Precious Metals IRA, they can roll it into their own IRA and continue deferring taxes under standard IRA rules. Non-spouse heirs who inherit a Precious Metals IRA must distribute the assets within 10 years of the original owner’s death under the SECURE Act rules — paying income tax on distributions as they occur. The step-up in basis that applies to personally held precious metals does not apply to IRA-held metals, because IRA assets have never been taxed — they are fully taxable as ordinary income when distributed, regardless of what the metals are worth.
This distinction between personally held and IRA-held precious metals is critical for estate planning. For heirs who will receive precious metals in the highest tax bracket, an inherited IRA’s 10-year distribution requirement can create significant tax cost. Consulting with a qualified estate planning attorney and tax advisor about the relative estate planning benefits of IRA-held versus personally held precious metals is worthwhile for investors with significant positions in both categories.
Naming beneficiaries on your IRA. Unlike personal property passed through a will, IRA assets pass directly to named beneficiaries — outside probate entirely. This is both an advantage (speed, privacy) and a risk (beneficiary designation errors can override your will). Review your Precious Metals IRA beneficiary designations regularly and ensure they reflect your current estate planning intentions.
Ensuring your heirs can physically access your precious metals after your death requires deliberate planning on two levels.
Home-stored metals. Your heirs need to know the safe location, the safe combination or key location, and the legal authority to access and remove the metals (typically established by letters testamentary from your estate). If you store metals in a home safe that no one else knows about or can open, those metals may require a locksmith or safe cracker to access — a process that should be planned for and funded in your estate. Our guide to storing gold and silver at home covers the full range of home storage considerations, including the access documentation that should accompany any serious home storage arrangement.
Depository-stored metals (IRA or personal). Metals held at a professional depository — whether in an IRA or in personal allocated storage — require your estate executor to contact the depository with appropriate legal documentation (death certificate, letters testamentary) to transfer or liquidate holdings. The depository process is generally straightforward when documentation is complete. Ensure your estate executor knows the depository name, account number, and contact information.
Valuation for estate purposes. Precious metals must be valued at fair market value at the date of death for estate inventory purposes. Spot price at the date of death is the standard valuation basis — the same basis used for how spot price works in daily transactions. Your estate executor should obtain and document spot prices on the date of death for every metal category you hold.
The estate planning advantages of physical precious metals — step-up in basis eliminating lifetime appreciation from capital gains, direct physical transfer without institutional intermediary, permanent real value that requires no counterparty to maintain — make them among the most effective multi-generational wealth transfer vehicles available to ordinary investors.
A Gold Eagle given to a grandchild as a gift today becomes part of that grandchild’s estate decades hence, with the potential for another step-up in basis at death. A sealed Monster Box of Silver Eagles maintained across generations retains its original sealed documentation and sovereign mint credibility across every ownership transfer. Physical precious metals do not have account numbers that can be lost, institutions that can fail, or counterparties that can default. They exist independently of every system that ordinary financial assets depend on — which is why central banks have held them for centuries and why individual investors who think in multi-generational terms continue to accumulate them.
Q: Do my heirs pay capital gains when they inherit my gold and silver?
A: Not on appreciation that occurred during your lifetime. Physical precious metals inherited at death receive a step-up in basis to fair market value at the date of death — meaning your heirs’ capital gains calculation starts from that value. If they sell at the inherited value, they owe zero capital gains on the appreciation that occurred while you owned the metals. Only future appreciation above the inherited value is taxable when they eventually sell.
Q: Should I include precious metals in my will specifically?
A: Yes — explicitly naming your precious metals in your will (“my gold coins, silver bars, and all precious metals bullion”) with specific beneficiary designations is far cleaner than relying on catch-all “tangible personal property” language. If you want specific pieces to go to specific people, identify them by description and serial number. Work with an estate attorney to ensure the language is clear and legally effective in your jurisdiction.
Q: What happens to Gold IRA metals when I die?
A: IRA-held precious metals follow IRA inheritance rules, not estate inheritance rules. Spouse beneficiaries can roll the IRA into their own. Non-spouse beneficiaries must distribute the assets within 10 years under SECURE Act rules — paying income tax as ordinary income on distributions. The step-up in basis that applies to personally held metals does not apply to IRA-held metals. Consult an estate planning attorney and tax advisor for your specific situation.
Q: How do I establish the value of my gold and silver for estate purposes?
A: Use the gold and silver spot price on the date of death as the valuation basis — the same spot price quoted on financial data services and used in daily precious metals transactions. Document this price for every metal you hold. Your estate executor should obtain and record spot prices on the date of death. Individual coins and bars are valued at spot price plus any applicable numismatic or collector premium for pieces that carry collector value above metal content.
Q: What is the most important practical step I can take today for estate planning with precious metals?
A: Create and maintain a written precious metals inventory — every piece listed by product, weight, serial number, acquisition date, and purchase price — stored separately from the metals themselves. Tell your estate executor or a trusted family member that this inventory exists and where to find it. Ensure at least one trusted person knows where your metals are stored and how to access them. These three steps eliminate the most common and most costly precious metals estate planning problems.

Investment-grade gold, priced with the live market and fully insured.
Prices, new stock and new guides. No spam.
Walk into the numismatic side of any serious precious metals conversation and you will encounter a vocabulary that
Inflation is not an abstract economic concept — it is the measured, documented erosion of what your money
Among the analytical tools that serious precious metals investors use, one stands out for its simplicity and its
Email us and a real person will help you choose the right gold for you.